Reported by Simon Daniel Yusuph l Journalist at Weng Global
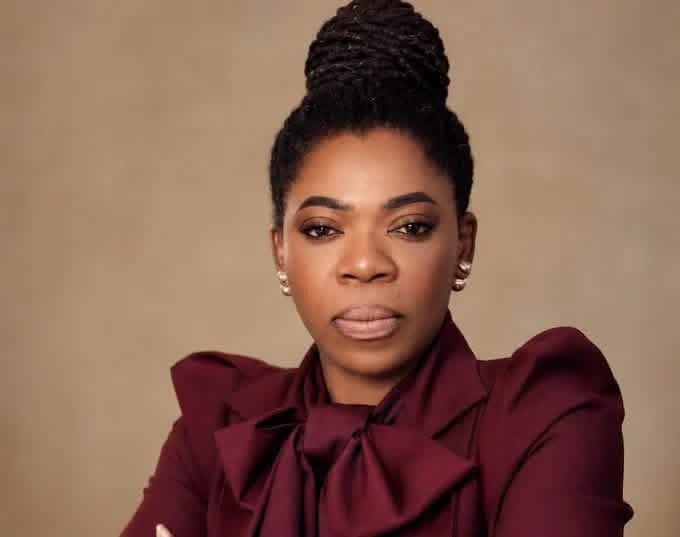
The Lagos State House of Assembly has approved the appointment of Dr. Olufunke Omolara Tayo-Makanjuola as the substantive Auditor-General of Lagos State, following her nomination by Governor Babajide Sanwo-Olu.
The confirmation was granted during plenary on Monday, November 9, 2026, after lawmakers considered and approved her screening report.
The development marks a new stage in the leadership of the Office of the State Auditor-General, which is responsible for examining public accounts and supporting accountability in the management of government resources.
Following the approval, the Speaker of the House, Mudashiru Obasa, directed the Clerk, Adenike Oshinowo, to forward the Assembly’s resolution to Governor Sanwo-Olu for his assent.
The Office of the State Auditor-General subsequently announced the confirmation, describing it as an important milestone in Tayo-Makanjuola’s career in the Lagos State Public Service.
Her appointment follows her earlier nomination as Acting State Auditor-General in July 2026, when the governor initiated the process subject to legislative confirmation.
From Acting Auditor-General to Substantive Appointment
Before her nomination as Acting State Auditor-General, Tayo-Makanjuola served as Head of the Directorate of Government Accounts.
Her responsibilities in that position placed her within the state’s public financial management structure, where government accounting processes and financial records form an important part of administrative operations.
Governor Sanwo-Olu’s nomination in July followed the issuance of Circular No. CIR/HOS/’26/052 by the Office of the Head of Service. The circular, dated July 28, 2026, conveyed her appointment, which took effect from that date.
At the time, the nomination remained subject to confirmation by the Lagos State House of Assembly.
The lawmakers’ approval on November 9 therefore represents the next major step in the appointment process.
The resolution was subsequently directed to the governor for assent. The available announcement does not establish the date on which the assent will be completed or when she will formally assume the substantive position.
Professional Background and Academic Qualifications
Tayo-Makanjuola has an academic and professional background in accounting, business administration and public financial management.
According to information released by the Office of the State Auditor-General, she holds a Doctorate in Business Administration in International Business from Lagos State University, Ojo.
She is also a fellow and member of several professional organisations, including the Institute of Chartered Accountants of Nigeria (ICAN), the Association of National Accountants of Nigeria (ANAN), the Chartered Institute of Taxation of Nigeria (CITN), the Chartered Institute of Directors (CIoD) and the Chartered Institute of Financial Practitioners (CFIP) in the United States.
Her professional affiliations reflect involvement in fields connected to accounting, taxation, financial management and corporate governance.
The Office of the State Auditor-General said her confirmation recognises her professional experience, qualifications and capacity to provide leadership in the state’s public sector auditing system.
However, the practical impact of her appointment will ultimately be assessed through the performance of the office and its contribution to transparent financial administration.
What the Auditor-General’s Office Does
The Auditor-General occupies an important position in public financial management because the office provides an independent mechanism for examining how public funds are accounted for and used.
In Lagos State, the Office of the Auditor-General is expected to examine government financial records and assess whether public accounts comply with applicable financial regulations and procedures.
The work of the office is relevant to ministries, departments and agencies responsible for implementing government policies and delivering public services.
Auditing helps identify weaknesses in financial controls, irregularities in accounting procedures and areas where public institutions may need to improve their management of resources.
It also provides information that can support legislative oversight and public scrutiny of government spending.
The office’s responsibilities therefore extend beyond the preparation of financial reports. Its findings can help strengthen institutional controls and encourage public bodies to maintain proper records of expenditure and revenue.
For a state with a large public administration and substantial infrastructure and social development responsibilities, effective auditing is particularly important.
Why the Appointment Matters for Lagos State
Lagos is Nigeria’s commercial centre and one of its most economically significant states. Its government manages public resources across several sectors, including transportation, healthcare, education, infrastructure, housing and environmental management.
The scale of these responsibilities makes financial accountability an important part of public administration.
Government revenue, allocations, internally generated revenue and other public funds must be properly recorded and accounted for. Without effective auditing and oversight, weaknesses in financial management can reduce public confidence and affect the efficient delivery of government services.
The Auditor-General’s office provides an institutional mechanism for examining these processes.
A properly functioning audit system can help government institutions identify financial management weaknesses, improve record-keeping and strengthen compliance with established procedures.
It can also provide lawmakers and other oversight institutions with information needed to assess the handling of public resources.
Tayo-Makanjuola’s confirmation therefore comes with significant professional responsibilities, particularly in maintaining the credibility and effectiveness of the state’s public auditing arrangements.
Her leadership will be important in ensuring that the office carries out its duties with professionalism, independence and attention to established auditing standards.
Accountability and the Importance of Independent Auditing
Public auditing is a key element of responsible government because the management of public funds affects citizens directly.
Money allocated to roads, hospitals, schools, public transportation and other services must be properly accounted for. Financial oversight helps establish whether public institutions have maintained the required records and followed relevant financial procedures.
The Auditor-General’s work can also contribute to identifying weaknesses that require administrative corrections or further investigation by appropriate authorities.
However, auditing is most effective when findings receive proper attention from the institutions responsible for implementing recommendations and addressing identified shortcomings.
The office must also be able to carry out its duties professionally and without improper interference.
For Lagos residents, the value of the appointment will not be measured simply by the announcement of a new officeholder. It will depend on the quality of financial oversight, the timeliness of audit work and the extent to which findings contribute to stronger accountability.
The confirmation also provides an opportunity for the state to reinforce public confidence in the institutions responsible for monitoring government expenditure.
Office Reaffirms Commitment to Transparency
Following the confirmation, the management and staff of the Office of the State Auditor-General congratulated Tayo-Makanjuola and expressed confidence in her ability to lead the institution.
The office reaffirmed its commitment to supporting her leadership in strengthening public sector auditing, promoting transparency and accountability, and encouraging prudent management of public resources.
The statement also described her confirmation as recognition of her professional competence and experience.
While the office expressed confidence in her leadership, the broader responsibility of strengthening accountability will require cooperation across government institutions.
Ministries, departments and agencies must maintain accurate financial records and respond appropriately to audit requirements. Legislative oversight and the implementation of relevant recommendations also remain important parts of the accountability process.
What Happens Next?
With the Lagos State House of Assembly approving her appointment, the next formal step identified in the legislative proceedings is the forwarding of the House’s resolution to Governor Sanwo-Olu for assent.
The completion of the process will pave the way for Tayo-Makanjuola to take up the substantive position in accordance with the applicable procedures.
The available information does not specify a date for the governor’s assent or her formal assumption of office.
Attention will subsequently turn to the performance of the Office of the State Auditor-General under her leadership, particularly its role in examining public accounts and strengthening financial accountability across Lagos State.
For residents, the central expectation is that the office will continue to provide credible oversight of public finances and support responsible management of resources meant for public development.
Tayo-Makanjuola’s confirmation is an important administrative development, but its lasting significance will depend on how effectively the office fulfils its constitutional and institutional responsibilities.
Weng Global – stories beyond borders
Sources
- Office of the State Auditor-General, Lagos State
- Lagos State Government
- Lagos State House of Assembly proceedings, as reported by Tribune Online
- Vanguard
- The Punch