Reported by Simon Daniel Yusuph l Journalist at Weng Global
Consolidated Hallmark Insurance Limited and CHI Life Assurance Limited have called for deeper collaboration with insurance brokers and other industry stakeholders as Nigeria’s insurance sector enters a new phase focused on stronger customer service, innovation and wider market penetration.
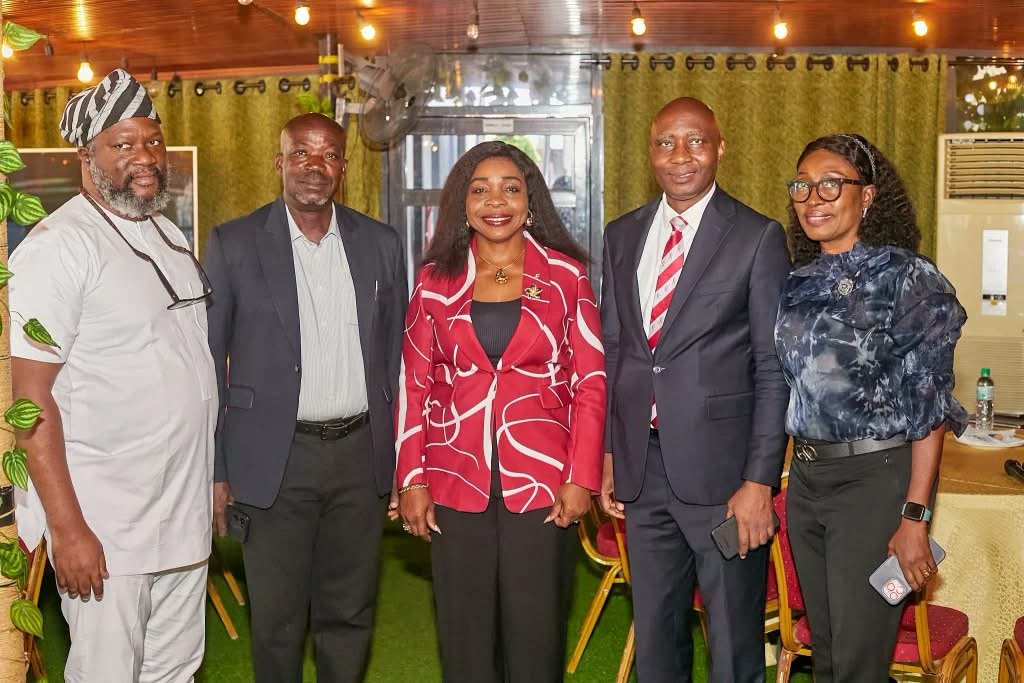
The call was made at the recently concluded Ibadan Professional Brokers Forum, where senior executives from the two companies engaged insurance brokers on ways to strengthen relationships across the insurance value chain and create solutions that respond more effectively to customers’ needs.
The companies, both members of Consolidated Hallmark Holdings Plc, said insurers could not build the next phase of Nigeria’s insurance industry alone. They stressed that stronger cooperation among insurers, brokers and other stakeholders would be necessary to improve public confidence, identify gaps in the market and develop products capable of addressing emerging risks.
The forum brought together key industry participants, including Consolidated Hallmark Insurance Managing Director and Chief Executive Officer Mary Adeyanju, CHI Life Assurance Managing Director and Chief Executive Officer Tope Ilesanmi, Executive Director of Operations at CHI Limited Jimalex Orjiako, Regional Director for Retail West Ose Oluyanwo and Managing Director of BFOA Insurance Brokers Bolaji Ayejuyo.
Focus Shifts to Collaboration and Customer Needs
The discussions in Ibadan came at a significant moment for Nigeria’s insurance industry.
The sector has recently completed a major recapitalisation exercise designed to strengthen the financial capacity of insurance operators and position them to take on larger risks. The National Insurance Commission announced in August that the recapitalisation exercise had entered a new phase following the verification of compliant insurance and reinsurance companies.
NAICOM said the exercise was intended to create a stronger, more resilient and adequately capitalised industry capable of supporting economic growth, improving policyholder protection, mobilising long-term investment and deepening financial inclusion.
The conclusion of the recapitalisation process means the conversation within the industry is increasingly moving from capital requirements to what companies can do with stronger financial foundations.
For Consolidated Hallmark and CHI Life, the Ibadan forum provided an opportunity to emphasise that stronger capital must be accompanied by stronger relationships, better products, effective distribution and improved customer experience.
This places insurance brokers at an important point in the industry’s development because brokers often serve as a bridge between insurance companies and policyholders.
Adeyanju: Brokers Are Close to the Reality of Insurance
Speaking at the forum, Mary Adeyanju highlighted the importance of insurance to business continuity and recovery.
She explained that business continuity involves ensuring that a company can continue operating even after suffering a major disruption or catastrophe.
The point is particularly relevant for Nigerian businesses facing risks ranging from fire and accidents to theft, natural hazards, business interruption and other unforeseen events.
Adeyanju also placed brokers at the centre of the insurance value chain because of their relationship with policyholders and their understanding of customers’ experiences when claims arise.
She said brokers are often among the first points of contact when customers experience losses and therefore have direct knowledge of the challenges faced by policyholders.
That proximity, she suggested, gives brokers an important role beyond simply distributing insurance products.
Brokers can provide insurers with information about what customers actually need, where existing products are failing to meet expectations and which emerging risks require new solutions.
Adeyanju consequently encouraged brokers to work more closely with underwriters to identify market gaps and develop products that address real problems.
The approach reflects a broader shift in insurance towards customer-centred product development rather than relying solely on traditional products and distribution channels.
Why Brokers Matter to Insurance Growth
Insurance brokers occupy a strategic position within the industry’s distribution and advisory structure.
For many individuals and businesses, insurance can be difficult to understand because policies contain technical terms, conditions, exclusions and different levels of coverage.
A professional broker can help customers assess risks, compare available coverage and understand the implications of different policies.
Brokers can also assist in the claims process and maintain relationships with both policyholders and insurers.
That makes the relationship between insurers and brokers particularly important in a market where public trust remains a major factor in insurance adoption.
If customers do not understand what they are purchasing or do not believe claims will be handled fairly and efficiently, they may be reluctant to take up insurance.
The companies’ emphasis on stronger broker partnerships therefore goes beyond commercial interests. It also touches on the wider challenge of building confidence in insurance as a practical financial protection tool.
CHI Life Pushes Innovation and Deeper Penetration
For CHI Life Assurance, the forum also provided an opportunity to reinforce its focus on expanding life insurance in Nigeria.
Tope Ilesanmi, the company’s Managing Director and Chief Executive Officer, called for closer cooperation between life insurers and brokers while stressing the importance of innovation and customer-focused solutions.
CHI Life has positioned technology and professional service as important components of its strategy to expand life assurance in Nigeria. The company formally commenced business operations in March 2025 after receiving its operational licence and has identified deeper insurance penetration as a central part of its business objectives.
The company offers products including term assurance, whole-life plans, endowment plans, group life and keyman assurance.
These products address different financial protection needs, ranging from family protection and long-term planning to employee benefits and protection against the financial consequences of losing key personnel in a business.
For brokers, understanding these products and matching them to appropriate customer needs can help make life insurance more accessible to Nigerians who may not traditionally consider it part of their financial planning.
Trust Remains Central to Insurance
The question of trust was another important element of the wider conversation around broker relationships.
Insurance operates on a promise: customers pay premiums in anticipation that the insurer will provide financial protection when a covered loss occurs.
That promise can only function effectively when customers have confidence in the insurer, understand their obligations and believe that legitimate claims will be handled according to the terms of their policies.
CHI Life has previously described trust as a fundamental element of the insurance relationship, linking it to the promises insurers make, the claims they settle and the relationships they build with customers.
Brokers can contribute to that trust by helping customers understand policies before they purchase them and by maintaining professional relationships throughout the life of the policy.
Insurers, on the other hand, must support that relationship through efficient underwriting, transparent communication, timely claims handling and consistent service.
The stronger these relationships become, the greater the possibility of improving customer confidence.
Nigeria’s Insurance Industry Enters a New Phase
The Ibadan forum took place against the backdrop of the recently completed insurance recapitalisation exercise.
NAICOM announced in August 2026 that 43 insurance and reinsurance companies had initially met the new minimum capital requirements following the 12-month exercise conducted under the Nigerian Insurance Industry Reform Act 2025. The regulator subsequently confirmed seven additional insurers, bringing the number of compliant insurance companies to 48 alongside two reinsurance companies.
The new capital regime requires minimum capital levels of N15 billion for non-life insurers, N10 billion for life insurers, N25 billion for composite insurers and N35 billion for reinsurers, subject to the applicable regulatory framework and risk-based requirements.
The recapitalisation was designed to strengthen insurers’ financial capacity.
However, capital alone does not automatically translate into greater insurance penetration.
Companies still need effective distribution networks, customer trust, appropriate products, technology, skilled professionals and efficient claims processes.
This is where the relationship between insurers and brokers becomes increasingly important.
From Recapitalisation to Market Expansion
The next test for the industry is how effectively the stronger financial base created by recapitalisation can be converted into actual growth.
NAICOM has said the post-recapitalisation period should support greater capacity to underwrite larger and more sophisticated risks while improving the industry’s ability to protect policyholders and contribute to the wider economy.
For companies such as Consolidated Hallmark Insurance and CHI Life Assurance, this creates opportunities to expand their reach and develop new areas of business.
But expansion will depend partly on whether insurers can reach customers who remain outside the formal insurance market.
Nigeria has a large population and a substantial business community, yet insurance remains underused compared with its potential.
NAICOM’s Insurance Sector Strengthening Programme, launched in September 2026, is targeting an increase in insurance penetration from about 0.5 per cent of GDP to 1.5 per cent by 2028. The programme focuses on strengthening the sector, rebuilding public trust and making insurance more inclusive and accessible.
The target demonstrates the scale of the opportunity facing the industry.
It also shows why stronger cooperation between insurers and brokers is becoming increasingly important.
Customer-Centred Products Could Drive Growth
One of the strongest messages emerging from the Ibadan discussions is the need to develop products around actual customer needs.
Insurance companies can have technically sound products, but those products will have limited impact if customers do not understand them, cannot afford them or do not see their relevance.
Brokers can help close this gap because they interact directly with customers and businesses.
They can identify recurring concerns and communicate those concerns to insurers.
For example, a business owner may require protection against interruptions to operations but may not know which insurance product addresses the risk. A broker who understands the customer’s operations can help identify appropriate coverage and explain its limitations.
The same principle applies to individuals considering life assurance.
Customers have different financial circumstances, family responsibilities and long-term goals. A product that suits one person may not necessarily be appropriate for another.
Greater collaboration between insurers and brokers can therefore encourage more tailored solutions.
Technology and the Future of Insurance
Technology is also expected to play a major role in the next stage of insurance development.
CHI Life has identified technology as part of its strategy for deepening insurance penetration, while the wider regulatory environment is increasingly focused on modernising the Nigerian insurance ecosystem through innovation and digitisation.
Digital tools can make it easier for customers to obtain information, compare options, communicate with insurers and access services.
They can also improve internal processes for insurance companies, potentially reducing delays and improving the management of customer information.
However, technology will not eliminate the importance of human relationships.
Insurance remains a product built around trust, risk assessment and financial protection. Customers may still require professional guidance, especially when dealing with complex policies or significant financial exposures.
This means the future is likely to require a combination of technology and professional advice rather than one replacing the other.
The Broader Economic Importance
A stronger insurance sector can have implications beyond insurance companies themselves.
Insurance helps businesses manage risk and recover from unexpected losses. It can therefore support continuity of economic activity when companies experience adverse events.
A stronger insurance industry can also contribute to financial stability by providing mechanisms for transferring and pooling risk.
For households, appropriate life and general insurance products can provide protection against financial shocks.
For government, a more developed insurance market can support broader financial inclusion and reduce some of the pressures created when individuals and businesses face losses without adequate protection.
This explains why the industry’s growth is relevant to Nigeria’s wider economic development agenda.
The challenge is not simply to sell more insurance policies but to ensure that the products being purchased provide meaningful protection and that customers understand the value of that protection.
A Relationship That Must Produce Results
The call for deeper broker partnerships will ultimately be measured by results.
Stronger relationships should lead to better communication between insurers and brokers, faster responses to customer needs, more relevant products and improved service delivery.
They should also contribute to higher public confidence.
The companies’ engagement with brokers in Ibadan follows similar efforts elsewhere in Nigeria.
In August, Consolidated Hallmark Insurance and CHI Life Assurance also participated in a Professional Brokers’ Evening organised by the Nigerian Council of Registered Insurance Brokers in Abuja, where they stressed collaboration, innovation and industry capacity.
The companies also engaged brokers in the South-South region, where discussions focused on the next phase of growth following the recapitalisation exercise.
The repeated engagement indicates that broker relationships are becoming a significant part of the companies’ strategy as the insurance industry moves into its post-recapitalisation phase.
What Happens Next
The immediate challenge for Consolidated Hallmark Insurance, CHI Life Assurance and their broker partners is to translate the commitments made at the Ibadan forum into practical improvements.
That means identifying underserved customer segments, developing relevant insurance solutions, improving communication and strengthening the process through which customers access insurance and make claims.
The wider industry faces the same task.
Nigeria now has a more strongly capitalised insurance market following the recapitalisation exercise, but stronger balance sheets must eventually translate into stronger customer confidence, wider coverage and deeper penetration.
Brokers will remain important in that process because of their direct connection with policyholders and businesses.
For Consolidated Hallmark Insurance and CHI Life Assurance, the Ibadan forum has therefore reinforced a central message: the future growth of Nigerian insurance will depend not only on the strength of individual companies but also on how effectively the industry’s different participants work together.
The success of that approach will ultimately be judged by whether more Nigerians see insurance as accessible, understandable and valuable to their everyday lives and businesses.
Weng Global – stories beyond borders
Sources: Consolidated Hallmark Insurance; CHI Life Assurance; National Insurance Commission; The PUNCH; BusinessTodayNG; Daily Economy.