Reported by Weng Patrick Atokor l Journalist at Weng Global
Nigeria has numerous agricultural financing initiatives, yet many farmers and agribusinesses continue to face difficulty obtaining suitable credit.
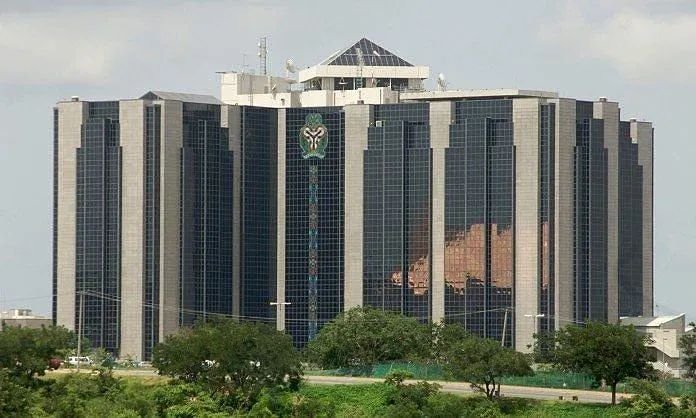
A recent warning from the Central Bank of Nigeria (CBN) has highlighted an important part of the problem: the challenge is not simply that there is too little money available for agriculture.
According to CBN Deputy Director and Special Assistant in the Office of the Deputy Governor, Economic Policy Directorate, Dr Michael Ononugbo, inadequate infrastructure and insufficient funding for agricultural research are among the structural weaknesses limiting agricultural finance in Nigeria. He made the remarks at the National Close-Out Conference of the Global Project for the Promotion of Agricultural Finance for Agri-based Enterprises in Rural Areas, known as GP AgFin Nigeria, in Abuja.
The issue raises a broader question: Why can farmers still struggle to obtain useful agricultural finance when Nigeria has spent years developing schemes designed to support the sector?
The problem is bigger than a shortage of money
Agricultural finance is often discussed as if the solution is simply to make more loans available.
But farming does not operate like many conventional businesses.
A farmer may need money months before harvesting a crop. A poultry farmer may have to buy feed continuously before receiving income from sales. A fish farmer has to spend money on fingerlings, feed, labour and water management before the fish reach market size.
This means that the timing, cost and structure of a loan can be just as important as the amount borrowed.
Ononugbo said Nigeria’s agricultural finance gap was rooted in structural weaknesses and not simply a shortage of capital. He warned that financing that is poorly structured, expensive, delivered late or disconnected from agricultural production cycles may fail to improve productivity and could increase borrowers’ vulnerability.
In simple terms, a loan can exist without being the right loan for a farmer.
Why infrastructure matters to agricultural lending
Infrastructure may appear to be separate from banking, but it directly affects the risks faced by farmers and lenders.
Poor roads can make it difficult and expensive to move farm produce to markets.
Insufficient storage can force farmers to sell immediately after harvest, when prices may not be favourable.
Limited processing facilities can prevent farmers from turning raw agricultural products into higher-value goods.
Weak electricity and other infrastructure can also increase production and operating costs for agricultural businesses.
These problems matter to lenders because agricultural loans are expected to be repaid from the income generated by the financed business.
If a farmer cannot efficiently produce, store, process or transport goods, the ability to repay a loan can be affected.
Research published through the CBN’s Economic and Financial Review has also examined the relationship between rural infrastructure and food security, highlighting the role of physical and organisational infrastructure in production, processing and distribution.
Why agricultural research is part of the finance problem
The CBN’s warning also points to another issue that receives less attention: agricultural research.
Ononugbo questioned how much financing is being directed towards agricultural research and innovation, arguing that inadequate investment could limit the development of solutions capable of improving productivity.
This matters because finance alone cannot solve every agricultural problem.
A farmer who receives credit but continues to use inefficient production methods may not achieve enough productivity to generate sustainable returns.
Research and innovation can contribute to improved seeds, farming methods, animal breeds, disease control, irrigation, storage, processing and other technologies.
When productivity improves, farmers can potentially generate stronger businesses. That can also make agricultural enterprises more attractive to financial institutions.
The relationship therefore works in both directions: better finance can support agricultural development, while stronger agricultural businesses can make financing more productive and sustainable.
Why banks can be cautious about lending to farmers
Agriculture contains risks that can make conventional lending difficult.
Farmers can face weather shocks, diseases, changing commodity prices, production losses and market disruptions.
Many smallholder farmers also operate informally, with limited financial records.
A farmer may have land, livestock or a viable agricultural business but lack the formal documentation or conventional collateral required by a financial institution.
These challenges can make it difficult for a bank to assess the farmer’s ability to repay a loan.
Nigeria’s agricultural finance system has therefore attempted different approaches to address the gap.
The National e-Agriculture Portal, for example, lists several agricultural credit mechanisms, including the Agricultural Credit Guarantee Scheme, Commercial Agriculture Credit Scheme and other financing arrangements designed to support agricultural enterprises.
The existence of such schemes demonstrates that agricultural finance is not a new policy concern in Nigeria.
The continuing challenge is making financing work effectively for the realities of agricultural production.
What GP AgFin Nigeria shows
The experience of GP AgFin Nigeria provides an example of how agricultural finance can be approached differently.
The eight-year project, funded by Germany’s Federal Ministry for Economic Cooperation and Development and implemented by GIZ, worked to improve access to financial services for farmers and agribusinesses.
GIZ says the project focused on financial services tailored to agricultural businesses and rural enterprises, including financial literacy and training.
Recent reporting on the project’s national close-out conference said more than 101,000 farmers and agribusinesses had accessed adapted financial products and services through the programme.
The project also supported financial institutions in developing agricultural finance products suited to different value chains. According to the reported figures, 22 products were developed and piloted, with 19 subsequently integrated into partner institutions’ portfolios.
This is important because it illustrates a central lesson in agricultural finance: farmers may need financial products designed around the agricultural business cycle rather than conventional lending structures.
It is not only about getting a loan
Consider two farmers.
The first receives a loan that must be repaid before the farmer’s crop is harvested and sold.
The second receives financing with a repayment structure that reflects the farmer’s production and sales cycle.
Even if both farmers receive the same amount of money, their ability to use and repay the loans could be very different.
That is why the structure of agricultural finance matters.
A useful agricultural loan may need to consider:
- The crop or livestock cycle
- Production costs
- Expected harvest period
- Market access
- Storage capacity
- Commodity prices
- Insurance or risk-management mechanisms
- The farmer’s existing financial records
- The availability of collateral or alternative guarantees
The objective should therefore not simply be to increase the number of loans issued.
It should be to ensure that financing contributes to productive agricultural activity.
Why this matters for food security
Agricultural finance has implications beyond individual farmers.
Nigeria’s ability to produce food depends partly on whether farmers can obtain the resources needed to expand production, adopt technology and withstand economic shocks.
When farmers lack suitable financing, they may be unable to purchase inputs, expand their farms, invest in equipment or improve processing.
But finance must work alongside other parts of the agricultural system.
Credit cannot replace roads.
Loans cannot substitute for research.
Bank financing alone cannot solve storage shortages.
And money cannot eliminate every weather or market risk.
The broader lesson from the CBN’s intervention is therefore that agricultural finance needs to be considered as part of a larger agricultural ecosystem.
What needs to change?
The current debate points towards several areas that require attention.
First, agricultural finance needs to become more closely aligned with production realities.
Second, infrastructure investment needs to support the businesses receiving agricultural credit.
Third, agricultural research and innovation require sustained investment so that farmers can access better technologies and production methods.
Fourth, financial institutions need better information about agricultural value chains and the businesses operating within them.
Fifth, farmers and agribusinesses need stronger financial management skills, including record keeping, budgeting and understanding loan obligations.
The GP AgFin experience demonstrates that training and tailored financial products can form part of this approach. GIZ has previously described its Farmer Financial Cycle training as covering areas such as investments, loans, savings and personal financial management.
What happens next?
GP AgFin Nigeria is expected to formally conclude in October 2026, with its tools and partnerships expected to transition into another GIZ-supported programme.
The larger question will be whether the lessons generated by the programme can become part of Nigeria’s wider agricultural finance system.
For farmers, the issue is ultimately not simply whether a bank or government programme offers credit.
The more important question is whether the financing is affordable, timely, appropriately structured and connected to the realities of farming.
Nigeria has spent years creating agricultural financing schemes. The continuing challenge is ensuring that those schemes translate into productive investment, stronger farm businesses and improved access to markets.
Weng Global Explain
The CBN’s latest warning helps clarify why agricultural finance remains difficult in Nigeria: the finance gap is connected to problems beyond the banking system itself.
Farmers need capital, but they also need infrastructure, research, technology, market access, financial knowledge and financing arrangements that reflect how agricultural businesses actually operate.
That is the central distinction between simply providing agricultural loans and building an agricultural finance system capable of supporting sustainable production.
Weng Global – Stories beyond borders
Sources
- Central Bank of Nigeria — The Contribution of Finance to Agricultural Production in Nigeria.
- Central Bank of Nigeria — Rural Infrastructure and the Challenge of Food Security in Nigeria.
- Punch — Report on the CBN’s remarks concerning agricultural finance, infrastructure and research funding.
- GIZ — Empowering Future Farmers: The Journey of Institutionalisation.
- Vanguard — Report on GP AgFin Nigeria’s eight-year agricultural finance programme.