Reported by Weng Patrick Atokor l Journalist at Weng Global
A Senior Advocate of Nigeria (SAN), Dr Omogbai Omo-Eboh, has urged the Federal Government to strengthen implementation of Nigeria’s new insurance framework by ensuring that government assets and employees are adequately insured.
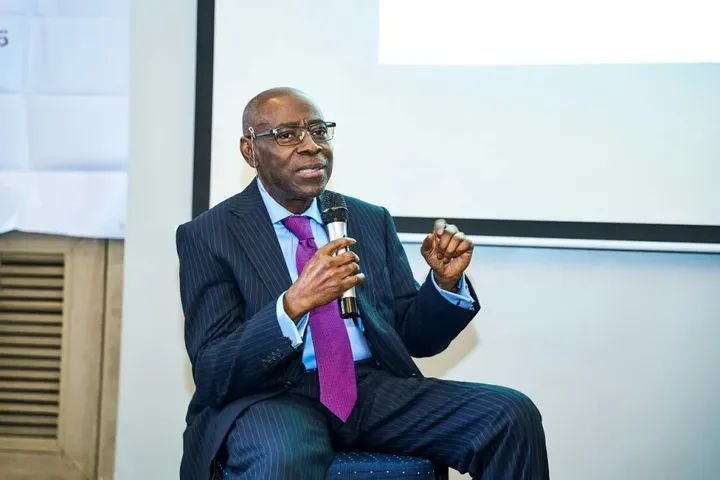
Omo-Eboh made the call during a two-day all-media inclusive seminar organised by Insurance Publication Limited in Lagos, where he argued that insurance should be integrated into public administration and fiscal planning rather than treated only as a private-sector financial product.
His comments come against the background of the Nigerian Insurance Industry Reform Act 2025 (NIIRA 2025), which introduced a consolidated legal framework for Nigeria’s insurance industry. President Bola Ahmed Tinubu assented to the legislation in August 2025, with the National Insurance Commission (NAICOM) responsible for administering and implementing the law.
What Omo-Eboh is asking the government to do
Omo-Eboh said the government should take a stronger role in ensuring compliance with compulsory insurance requirements and should use public digital platforms to make verification and enforcement easier.
According to reports from the seminar, he proposed that insurance checks be integrated into government systems responsible for licences, permits, registrations and public procurement. Such integration, he argued, could allow policy information to be verified electronically before certain government approvals are granted.
Among the examples he cited was vehicle licensing. He proposed that renewal of vehicle licences should involve real-time verification of compulsory motor third-party insurance.
He also called for evidence of appropriate insurance cover to be linked to other regulatory processes, including building approvals, certificates of completion and certain business-related clearances.
The proposal is aimed at moving insurance compliance away from a largely manual process and embedding it into routine interactions between citizens, businesses and government institutions.
NIIRA 2025 already provides for government insurance
The call is also connected directly to provisions contained in Nigeria’s 2025 insurance legislation.
Section 77 of the Nigerian Insurance Industry Reform Act 2025 provides that all assets and employees of the Federal Government and its agencies shall be insured against hazards and perils of a nature determined by NAICOM. The Act also gives the Commission responsibility for making regulations concerning the decision-making process for the relevant risks.
The law separately provides for group life assurance for employees.
Section 68 requires employers to maintain group life assurance for employees at a minimum of three times the employee’s annual total emolument. It specifically states that Ministries, Departments and Agencies of government are required to undertake the group life policies covered by the provision.
This means Omo-Eboh’s recommendation is not simply about creating a new category of government insurance. It also concerns effective implementation and enforcement of obligations already contained in the country’s current insurance framework.
Public buildings are also covered
The Act contains specific provisions concerning public buildings.
Section 76 requires every public building to be insured against hazards including collapse, fire, earthquake and storm, as well as other hazards that NAICOM may determine. The insurance is also required to cover certain legal liabilities associated with loss or damage to property and bodily injury or death involving users of the premises and third parties.
The legislation defines public buildings broadly to include certain buildings accessible to members of the public for purposes such as education, healthcare, recreation or business.
The law therefore creates a framework in which insurance is connected not only with government-owned property but also with wider public safety and liability risks.
Why the proposal matters for public finances
Omo-Eboh argued that adequate insurance coverage could reduce the financial pressure placed on government when unexpected losses occur.
Public infrastructure can be exposed to risks including fire, accidents, natural hazards, structural damage and liability claims. Without adequate insurance, the financial consequences of such events can fall directly on public budgets.
At the seminar, Omo-Eboh said insurance of public assets, public works and employees could reduce the state’s exposure to unexpected expenditure and allow public funds to be directed toward development rather than crisis response.
This is particularly relevant to fiscal planning because insurance transfers specified risks from the policyholder to an insurer in exchange for premiums, subject to the terms and limits of the policy.
The practical effect, however, depends on factors including adequate coverage, payment of premiums, proper valuation of assets, regulatory enforcement and insurers’ ability to meet legitimate claims.
Government’s role under the new insurance framework
NIIRA 2025 represents a significant restructuring of Nigeria’s insurance regulatory system.
The legislation repealed and consolidated several earlier insurance laws into a comprehensive framework covering insurance and reinsurance business in Nigeria. The State House said the reforms include measures relating to compulsory insurance, digitisation, policyholder protection and stronger regulatory oversight.
NAICOM is mandated to administer the law.
The legislation also provides for compulsory insurance in several areas beyond government assets and employees. These include public buildings, motor third-party risks, petroleum and gas-related risks, aviation and certain other categories.
Omo-Eboh’s argument is therefore part of a broader discussion about how the new legal framework can move from legislation to practical compliance.
Digital systems proposed for enforcement
A major element of the proposal is the use of digital technology.
Omo-Eboh said government platforms could be designed to verify insurance policy numbers before licences, permits or other approvals are issued.
The idea would potentially reduce dependence on physical documents and manual verification while making it easier for regulatory agencies to establish whether a required policy exists.
He also proposed using public services to facilitate premium collection, including through tax offices, licensing agencies or sector regulators at registration and renewal points.
Such a system would require coordination among government agencies, NAICOM, insurers and other relevant institutions.
It would also raise practical questions about data management, cybersecurity, interoperability, privacy, dispute resolution and the accuracy of insurance records. Effective implementation would therefore depend not only on legislation but also on detailed regulations and functioning digital infrastructure.
Insurance penetration remains a major issue
The discussions come as stakeholders continue to focus on Nigeria’s relatively low insurance penetration.
At the Lagos seminar, participants discussed ways to increase insurance coverage and improve public understanding of insurance. Reports from the event cited a target of raising insurance penetration from about 0.5 per cent of GDP to 10 per cent.
The precise measurement and interpretation of insurance penetration can vary depending on the methodology used, but the broader issue is the limited reach of formal insurance products among many Nigerians.
Omo-Eboh also advocated wider access to insurance products and stronger use of data in risk management.
Other stakeholders at the seminar called for increased public awareness and improved reporting of insurance-related issues.
Broader compulsory insurance requirements
The NIIRA 2025 framework extends beyond government assets.
For example, the law requires employers to maintain group life assurance for employees. It also requires public buildings to carry specified insurance coverage and provides for compulsory motor third-party insurance.
The Act further provides that insurance for goods and merchandise imported into Nigeria should be made with an insurer registered under the law.
These provisions illustrate the broader regulatory approach under NIIRA 2025: insurance is being incorporated into several areas of economic and public activity where uninsured losses can have consequences beyond an individual policyholder.
The effectiveness of that approach will depend on enforcement, affordability, awareness, availability of suitable insurance products and confidence that legitimate claims will be settled.
Other concerns raised at the seminar
The seminar also addressed the role of journalists in improving public understanding of insurance and other risk-related issues.
Dr Austin Aipoh, President of the Healthcare Providers Association of Nigeria, urged journalists to strengthen their watchdog role in reporting health misinformation. He specifically referred to issues including fake cures, unverified herbal remedies, misleading medical advertisements, vaccine misinformation and dangerous self-medication advice.
The discussion reflected the broader theme of the seminar, which examined the relationship between insurance, risk and journalism.
For the media, the issue extends beyond reporting insurance products. It also involves examining how public institutions comply with insurance requirements, how premiums are spent, whether assets are adequately covered and how claims are handled when insured risks occur.
What happens next
The immediate issue is implementation.
Although NIIRA 2025 establishes statutory requirements covering government assets, employees and public buildings, the practical operation of those requirements involves regulations, compliance systems and oversight by NAICOM.
Section 77 specifically assigns NAICOM responsibility for making regulations concerning the risks and decision-making process for insurance of Federal Government assets and employees.
Omo-Eboh’s proposals therefore place emphasis on enforcement and integration: government institutions would need systems capable of identifying assets and employees requiring cover, verifying policies and maintaining reliable records.
For Nigerians, the wider significance is that insurance could increasingly become part of routine government and business processes rather than an activity considered only after a loss has occurred.
The proposal also highlights a central challenge facing the sector: passing a comprehensive insurance law is one stage, while ensuring that its compulsory provisions are consistently understood, enforced and implemented is another.
As Nigeria continues implementing NIIRA 2025, the effectiveness of these measures will depend on cooperation among NAICOM, government ministries and agencies, insurers, businesses and the public.
The core question will be whether the new framework can translate statutory insurance requirements into measurable improvements in risk protection, compliance and confidence across the Nigerian economy.
Weng Global – Stories beyond borders
Sources
- National Insurance Commission (NAICOM), Nigerian Insurance Industry Reform Act, 2025 — including Sections 68, 76 and 77 on employee, public-building and government-asset insurance.
- State House, Abuja, announcement on President Tinubu’s assent to the Nigerian Insurance Industry Reform Act 2025.
- THISDAY, report on stakeholders’ call for integration of insurance checks into public digital platforms.
- Nigerian Tribune, report on integrating compulsory insurance into public services.
- The Eagle Online, report on Omo-Eboh’s presentation at the insurance and journalism seminar.
Image caption: Dr Omogbai Omo-Eboh, SAN, who called for stronger implementation of insurance requirements covering government assets and employees.
Image ALT text: Dr Omogbai Omo-Eboh SAN speaking on insurance reforms and government asset protection in Nigeria.